A fintech group that built its reputation lending to millions of Filipinos has now opened its doors to Malaysian borrowers. Skyro, a digital finance group, has rolled out its first credit product in Malaysia: a short-term cash loan that can be applied for, approved and paid out entirely through a mobile app. The launch, announced in Kuala Lumpur on 5 November 2026, makes Malaysia the company’s second market in Southeast Asia after the Philippines, where it began operating in 2022.
The timing is notable. Malaysia is in the middle of a push against illegal moneylending, including the unlicensed lenders popularly known as Ah Long and a growing wave of fraudulent loan apps. At the same time, the country’s consumer credit rules are being reshaped. Skyro is betting that a licensed, transparent and fully digital lender can find room in that environment, particularly among people who have a bank account but struggle to qualify for conventional bank loans.
What Skyro is offering
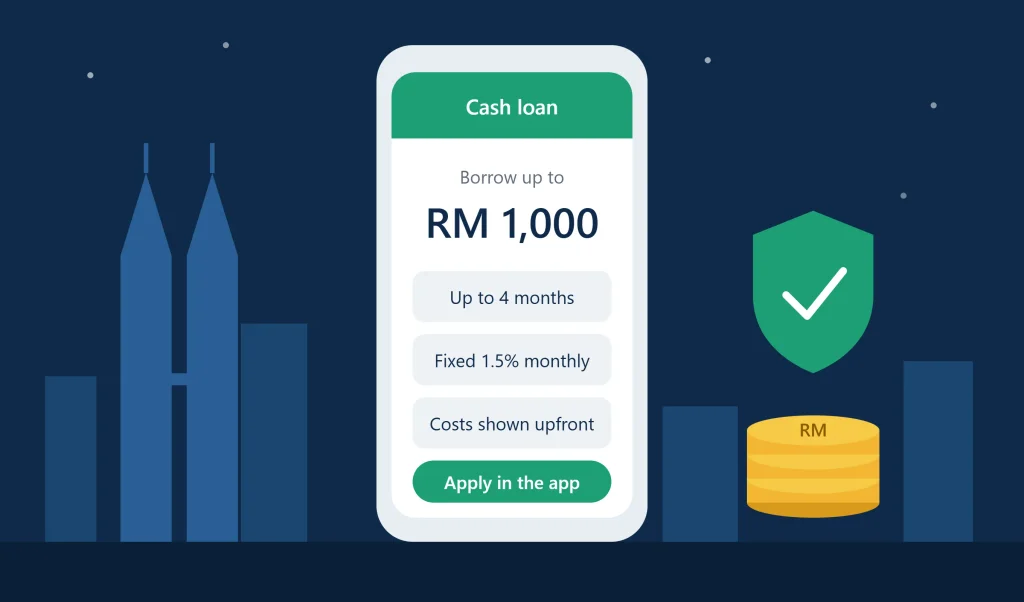
The first product is deliberately modest. New customers can apply for a cash loan of up to RM1,000, which is roughly US$250, with repayment spread over a period of up to four months. The loan carries a fixed interest rate of 1.5 per cent per month. Customers are shown the approved amount, the monthly instalments, any fees and the total they will repay before they sign, so there is no need to work out the cost after the fact.
Everything happens inside the Skyro mobile app. According to the company, identity verification, credit assessment, loan approval and disbursement are all handled digitally, and applicants never need to visit a physical branch or queue at a counter. For someone facing an unexpected bill, a delayed salary or a short gap before payday, the appeal is speed and simplicity.
To put the pricing in perspective, a fixed 1.5 per cent monthly rate works out to 18 per cent a year in nominal terms. On a RM1,000 loan, if interest is calculated on the original amount, the interest cost over four months would be around RM60, although the exact figure depends on how the rate is applied and on any fees, which the app is designed to disclose in full before acceptance. Borrowers comparing options should always look at the total repayment figure rather than the headline rate alone.
The RM1,000 ceiling is a starting point and not a destination. Skyro says it plans to increase borrowing limits step by step as it builds relationships with customers who repay on time, with a longer-term ambition of offering loans of up to RM10,000. The company also hopes to introduce a product with an approved credit limit, potentially before the end of 2026. That feature would let customers who have established a repayment record apply for later loans more easily, instead of going through a full application every time.
A licence first, a product second
Skyro did not rush to market. On 29 September 2026, it announced that its Malaysian entity had received a moneylender’s licence from the Ministry of Housing and Local Government, known by its Malay acronym KPKT. The licence authorises the company to conduct online moneylending in the country. At the time, Skyro said it would launch its first product in the coming months, and it has now done so within about five weeks.
Licensing matters in a market where borrowers can easily be lured by unregulated lenders. A licensed lender operates under supervision, must follow rules on disclosure and conduct, and can be held accountable if something goes wrong. Skyro is positioning that status as a selling point, framing its service as a safer and more transparent alternative for people who might otherwise be tempted by an unlicensed operator.
Why Malaysia, and why now
Malaysia has a population of around 35 million and a high level of bank account ownership. On paper, that suggests most people are financially included. In practice, access to a bank account is not the same as access to affordable credit. Consumers with thin credit histories, irregular income or no formal proof of salary can find it hard to be approved for a traditional personal loan, even when their repayment ability is reasonable.
That gap is where digital lenders see an opportunity. Data cited by Skyro indicates that Malaysia’s digital banks had approved about RM1 billion in financing by the end of 2025, and that 34 per cent of it went to customers who were unserved or underserved by conventional lenders. The figures suggest real demand for credit that is delivered through a phone, assessed quickly and designed around people who do not fit the template of a salaried, long-standing bank customer.
Skyro says it intends to use artificial intelligence and alternative data alongside conventional credit indicators when assessing applicants, an approach it has used in the Philippines and plans to adapt to Malaysian conditions and regulatory requirements. The idea is that a borrower with no extensive credit file may still show signs of reliability in other ways, allowing the lender to make a sound decision without relying only on traditional scores.
The regulatory backdrop
Skyro is entering Malaysia as the country’s consumer credit sector undergoes meaningful reform. The introduction of the Consumer Credit Act 2025 and the establishment of a Consumer Credit Commission signal a tighter and more coordinated approach to oversight of lenders that serve households. For responsible operators, clearer rules can be an advantage, since they raise the bar for conduct and make it harder for bad actors to undercut honest competitors.
The same environment brings obligations. Lenders will be expected to price transparently, communicate clearly and treat borrowers fairly. Skyro has emphasised responsible lending practices and has built its Malaysian launch around upfront disclosure of costs. Whether those commitments hold up as the business scales is something regulators, consumer groups and customers will watch closely.
The broader fight against illegal lending adds another layer. Loan sharks and fake loan apps cause real harm, from punishing interest to harassment and data misuse. Every licensed, transparent lender that wins customers is, in effect, one fewer pathway into that shadow market, provided the licensed option is actually accessible and affordable to those who need it.
What Skyro brings from the Philippines
The Malaysian launch rests on what the company says it has achieved at home. Skyro began lending in the Philippines in 2022 and has since disbursed more than US$600 million in loans. Its user base has passed 7 million. The company reported that it reached operating break-even in the first half of 2026, just over three years after launching, a milestone that gives it a degree of financial footing as it takes on a second market.
Its Philippine business extends beyond cash loans. The company’s products are offered through more than 3,000 merchants and around 10,000 retail locations, tying consumer financing to everyday purchases. Recent marketing efforts there have also linked digital credit with QR payments and with financing for appliances and energy-related relief. That variety hints at where Skyro could go in Malaysia over time, though for now the company is keeping its focus on cash loans.
The decision to start with a single product is telling. Skyro says it wants to learn how Malaysian consumers use credit, what they borrow for, how they repay and what they expect from a lender, then adapt its future offerings accordingly. The company describes a longer-term goal of building a broader financial services ecosystem in the market, not just a lending app.
What the founders are saying
Skyro’s co-founders have framed the launch as a measured first step. Co-founder and co-chief executive Arsen Liametov said the company is beginning with cash loans so it can better understand the needs of Malaysian consumers and the way they use credit. He also stressed that understanding costs and repayment is as important as getting access to credit in the first place, a message that echoes the company’s emphasis on clear disclosure.
When the licence was announced in September, co-founder and co-chief executive Nasim Aliev described a pattern he sees across Southeast Asia: hardworking people held back not by lack of effort but by a temporary cash gap between them and an opportunity. The company’s stated aim in Malaysia is to build credit products that bridge that gap while giving customers full control and transparency over their spending.
What borrowers should know before applying
A convenient loan is still a loan, and short-term credit works best when it is used deliberately. Here are some practical points for anyone considering the product.
First, read the full repayment summary. Skyro says customers can see the approved amount, instalments, fees and total repayment before signing. Compare that total with what you can comfortably afford each month, not only with what you need today.
Second, borrow only what you need. The first-loan limit of RM1,000 is small by design. Taking the maximum is not necessary if a smaller amount solves the problem.
Third, confirm that any lender you use is licensed. Malaysia’s authorities have repeatedly warned the public about unlicensed lenders and fraudulent loan apps. A genuine licensed lender will be able to point to its registration, and borrowers should be wary of anyone who asks for upfront fees, demands access to their contacts or applies pressure through threats.
Fourth, protect your personal data. Download apps only from official stores, check what permissions they request, and never share one-time passwords or banking credentials with anyone.
Finally, plan for repayment. Late payments can lead to extra charges and may affect your ability to borrow later. If you foresee difficulty, contact the lender early. Households that are already stretched should also consider free credit counselling services before taking on more debt.
Opportunities and open questions
There is a genuine case for what Skyro is trying to do. Many Malaysians work in gig, freelance or small business roles where income is real but hard to document. A lender that can assess such applicants fairly, price clearly and pay out quickly fills a gap that banks have not always covered. Competition from a new licensed player may also push other lenders to improve their own transparency and speed.
Still, important questions remain. A monthly rate of 1.5 per cent is not cheap, and consumer advocates in many markets argue that short-term credit should be used sparingly. The success of the model will depend on whether borrowers repay comfortably, whether limits increase responsibly and whether the company’s decision-making tools treat different groups of applicants fairly. Algorithmic credit scoring based on alternative data can expand access, but it also calls for strong safeguards around privacy and bias.
There is also the question of competition. Malaysia already has banks, digital banks, buy-now-pay-later services and other licensed moneylenders. Skyro will have to differentiate on user experience, clarity and trust, and it will need to prove that its Philippine success can be replicated in a market with different habits, regulations and expectations.
The road ahead
In the near term, watch for the introduction of the approved credit limit product that Skyro hopes to launch before the end of 2026, and for signs of how quickly borrowing limits rise for repeat customers. Over the longer term, the company’s ambitions point toward a wider set of financial services in Malaysia, building on the template it has used in the Philippines.
For now, the message from Skyro is straightforward: start small, learn fast and earn trust. For Malaysian consumers, the arrival of another licensed digital option adds choice at a time when the country is working to steer borrowers away from illegal lenders. Whether that choice proves to be a genuine improvement will be decided not by launch announcements but by how borrowers fare in the months ahead.
Skyro is a high-growth, digital-first fintech group that delivers scalable and responsible financial access across high-potential emerging markets. It launched in the Philippines in 2022 and has since disbursed more than US$600 million in loans to a user base of over 7 million, reaching operating break-even in the first half of 2026. Skyro uses AI and alternative data to assess creditworthiness and offers its products through its mobile app and a network of more than 3,000 merchants and about 10,000 retail locations. In September 2026, its Malaysian entity received a moneylender’s licence from Malaysia’s Ministry of Housing and Local Government, and in November 2026 it launched its first lending product in Malaysia, its second market in Southeast Asia.
Cosmopolitan The Daily is a digital publication delivering news, analysis and features on business, finance, globally minded readership. Its editorial team is committed to accurate, timely and accessible reporting, helping readers understand the developments that shape their money, careers and communities.